We built it for our children. Why should handing it over become harder after the Budget?
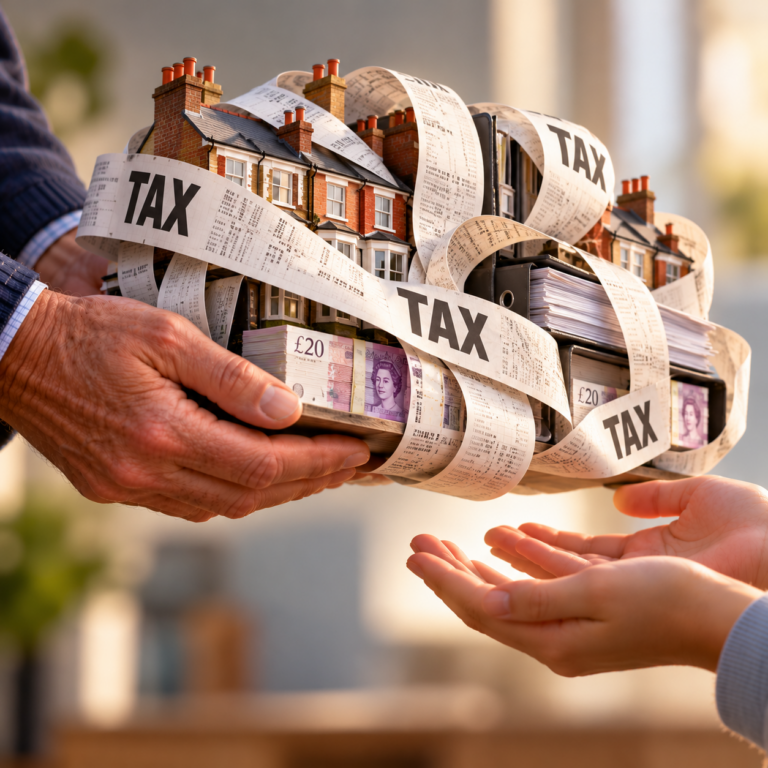
Build a business, pay your taxes and leave something worthwhile for your children. For many landlords, that has been the plan for decades. Reports that handing over a family company could become more expensive after the next Budget have struck directly at that ambition.
The anger is easy to understand. Owners fear another tax demand at the very point when they hoped to step back and let the next generation take over.
In the Facebook discussion we have seen, the frustration goes beyond this particular proposal. People question why hard work should attract further tax, whether government spends existing revenues wisely, and whether keeping a business going is still worth the effort.
Those comments do not establish what the proposed rules would do. They do explain why this story has hit a nerve.
What has prompted the backlash?
The Telegraph has reported that changes being considered ahead of the Budget could make some family business handovers more expensive. The concern involves arrangements where a departing owner receives payments for shares as part of passing the business on.
Payments currently treated as capital could instead be taxed as income. Depending on the circumstances, that could mean a larger bill and less money left for retirement.
For a landlord who has spent years building a property company, the immediate question is personal: will passing responsibility to my children now leave me with less to live on?
That is a serious concern. However, it is not the same as announcing a new tax on every parent who gives their children shares.
Why this feels like moving the goalposts
A family business can represent decades of saving, borrowing, repairs and financial risk. Its owner may have accepted those responsibilities partly because the business would eventually support the next generation.
Property also creates a particular problem: wealth on paper does not necessarily mean cash in the bank. A company can own valuable buildings while still needing its rental income to meet mortgage payments, maintenance bills and other costs.
If a handover requires more cash for tax, where does that money come from? Further borrowing? A smaller retirement income? Selling a property the family intended to keep?
These are possible consequences to examine, rather than outcomes we can already predict. But they explain why owners hear a headline about tax reform and worry about the future of everything they have built.
What the official documents actually say
The underlying document is HMRC’s consultation on modernising the distributions framework. In ordinary language, it examines how money and capital taken out of companies should be taxed.
The consultation closed in September. As at 20 October 2026, the proposals should not be presented as an enacted tax change.
Some proposals could affect arrangements used when owners retire or reorganise a business. The accountancy body ICAEW has raised concerns about their commercial consequences.
There is therefore a substantive issue behind the headlines. Equally, the documents do not establish a blanket 45% charge on the value of every family business handed to children.
Giving away shares, receiving payment for shares and recovering money genuinely lent to a company are different transactions. They need separate tax analysis. Existing taxes can also apply, even where these proposals are irrelevant.
For landlords, another important distinction is that some existing reliefs require a trading business. Owning a rental company does not automatically meet that requirement.
Government needs to explain where it draws the line
My concern is what happens to an ordinary, gradual retirement.
A parent may want to hand over management while receiving payments over time. The children may be capable of running the business without having enough money to buy it outright. The company still needs sufficient cash to operate.
Government is entitled to challenge arrangements designed to turn taxable income into capital simply to reduce tax. It must also explain how genuine family succession will remain workable.
Before introducing changes, ministers should show which arrangements they intend to catch, why existing safeguards are insufficient, and how families already planning a handover would be treated.
Owners deserve enough certainty to make decisions that will last longer than the next Budget.
Would a higher tax bill change your plans to pass on your property business, or is the greater problem no longer trusting the rules to stay reasonably predictable?
What does this mean for your family’s plans?
Our articles on leaving beneficiaries value rather than a burden and deciding which properties to sell first explore the wider choices around succession and retirement.
If you would like to discuss your own circumstances, a £400 Property118 consultation can help identify the options worth investigating and where specialist advice is needed.
Be the first to comment
Your experience could help the next reader
Have you dealt with something similar? Share what you learned, raise a question or offer a perspective your peers may find useful.
Previous Article
More than half of single-property landlords plan to leave the sector
Not a member yet? Join In Seconds
Login with