Tenants urged to ‘flood’ tribunals over rent rises
3 weeks ago | 36 comments


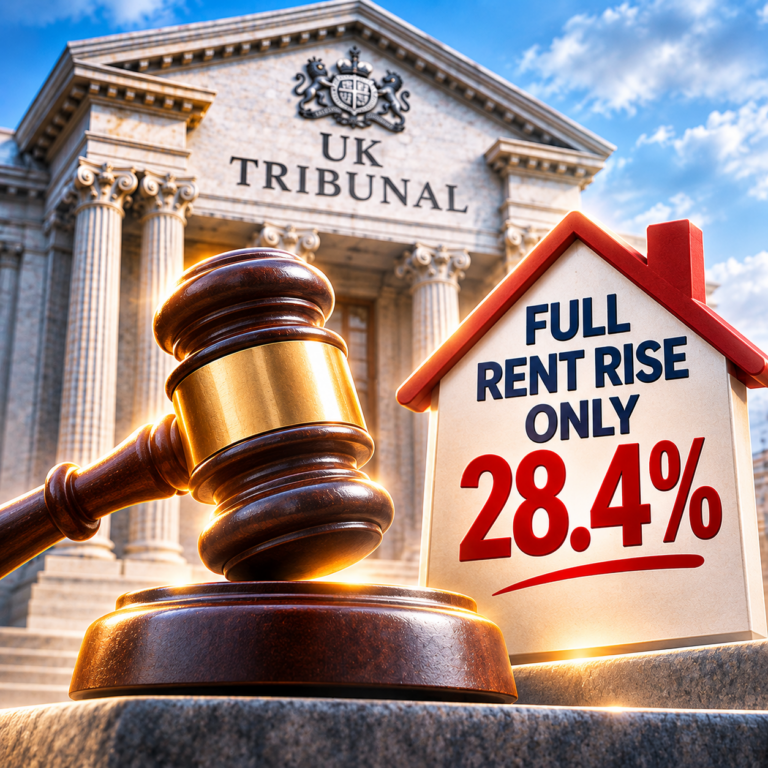
Landlords received their proposed rent increase in full in just 28.4% of tribunal cases decided in England in September.
Cyborg Finance examined 74 publicly available First-tier Tribunal decisions from September.
The remaining cases ended with a smaller increase than requested, an unchanged rent, a reduction or the case being struck out.
A strike-out does not determine a new rent.
Mark Hosker, a mortgage adviser at the firm, said: “The rent a landlord proposes and the rent a tribunal determines are not always the same.
“Landlords should be ready to support proposed rents with comparable local evidence, while tenants should remember that challenging an increase does not guarantee their rent will stay unchanged.”
He added: “More than two-thirds of September cases still resulted in an increase, with rents rising 6.7% overall.
“However, with a challenge potentially delaying higher rent payments by around four months, and nearly three-quarters of landlords failing to secure their full proposed increase, the £47 tribunal fee could prove money well spent.”
Of the cases examined, 21 resulted in the full proposed increase and 29 in a partial rise.
Rents were unchanged in 12 cases, reduced in six, and a further six cases were struck out.
Across the 68 cases with comparable original and determined figures, average monthly rent rose from £1,372 to £1,464.
That amounted to approximately £92 more a month, or £1,104 a year, with unchanged and reduced rents included in the calculation.
Cyborg Finance found that the aggregate rent increase for tribunal cases in September was 6.7%, compared with 6.3% in August.
The firm‘s wider tracker recorded an average of around 91 days between service of a landlord’s rent notice and a tribunal decision.
24 comments on this article
A different perspective could help you spot an issue, avoid a mistake or find a better way forward. Read the comments and add your own views if you wish.
Previous Article
Landlords face Saturday’s Making Tax Digital deadline
3 weeks ago | 36 comments
3 weeks ago | 51 comments
3 weeks ago | 8 comments
Member Since January 2025 - Comments: 147
3:24 PM, 3rd November 2026, About 1 week ago
… this is how the downward spiral begins, and anyone familiar with the political history of the Private Rented Sector should recognise the warning signs.
Rent Officers operated under a similar system under the Rent Act 1977, eventually allowing artificially depressed fair rents to become comparables for determining subsequent rents. The result was a self-perpetuating decline, detaching rental values from commercial reality.
Rent regulation, security of tenure and weakened investment incentives contributed to the PRS’s long decline until the Housing Act 1988 introduced assured and assured shorthold tenancies and Section 21 no-fault possession. Those reforms helped restore investor confidence and rebuild a sector reduced to a fraction of its former significance.
Along the way qualifying tenants gained statutory rights of first refusal on the sale of certain residential buildings under the Landlord and Tenant Act 1987, at values reflected by restricted rental income, tenants’ rights, security of tenure and repairing obligations. This will be the next stage in the current changes in legislation.
Now add the further capital expenditure required to meet increasingly demanding energy-efficiency and carbon-reduction objectives, alongside a taxation regime that takes little account of whether the underlying investment remains commercially viable.
And don’t imagine the Tribunal needs political instructions to deliver outcomes consistent with government policy. Parliament establishes the statutory framework, ministers implement regulations through established constitutional processes, and independent tribunals apply the resulting law. The political direction is embedded in the legislation itself.
Individually determined rents then become reference points for subsequent determinations. What begins as apparently independent market-rent decisions becomes a mechanism through which the market is progressively repriced.
And don’t take comfort from the apparent revival of interest in prime London property. That market is fundamentally different from the mainstream PRS affected by these reforms.
Residential tenancies commanding annual rents above £100,000 generally fall outside the assured tenancy regime to which the principal provisions of the Renters’ Rights Act 2025 apply. Prime central London property also attracts investors for reasons extending far beyond rental profitability. Gross yields are often modest relative to capital invested and may fall below the cost of geared finance. Nor has capital appreciation reliably compensated investors: values in September 2026 were approximately 26% below their 2014 peak in nominal terms, before inflation.
For many HNW and UHNW investors, London property is primarily a store of wealth rather than an income-producing business. The United Kingdom offers internationally established property rights, political and legal stability, and an independent judiciary. The attraction is the reasonable expectation of retaining ownership and recovering capital, not achieving an exceptional commercial return.
Rental yields are hardly the driving consideration.
For the government to present continuing investment by this category of wealth as evidence of the health of Britain’s mainstream PRS confuses different markets, investment objectives and measures of commercial success.
The real test is whether ordinary private investors, using their own capital, accepting commercial risk and paying for finance, maintenance, repairs, compliance and taxation, can earn an adequate return for providing homes.
The tragedy is that landlords may once again watch their investments dismantled through legislation, regulation, taxation and tribunal determinations.
Unless the political direction changes, the economic consequences are confronted, and the industry develops representative voices prepared to challenge the underlying legislation rather than take membership subscriptions simply to tutor landlords on how to comply with the progressive transfer of their wealth, the sector will repeat a history it ought to understand only too well.
Member Since September 2022 - Comments: 49
6:51 PM, 3rd November 2026, About 1 week ago
I would urge all Landlords to check out the Tribunal decisions, link provided by @seethinglandlord.
It’s certainly an eye opener and I would challenge some of the headline stats in this article having read some.
Market rent for the Tribunal in quite a few cases is in the same ballpark as the landlords / agents thoughts, however, the tribunal discounts the rent for things such as the landlord not providing white goods, lack of insulation, poor decor, dated windows and radiators and my favourite deterioration in the toilet floor (£50/month reduction for that one). The problem is that it’s not consistent and not always set out in a list.
Another ones stands out. The Landlord was awarded a 364% rent increase which was still below his request.
Others include the Landlord achieving their request knowing it was below market rent because it was “dated” etc.
So whilst the headline stats may be true, as always, the devil is in the detail!
Member Since September 2024 - Comments: 124
7:48 PM, 3rd November 2026, About 1 week ago
Reply to the comment left by Seething Landlord at 03/11/2026 – 12:55
If I remember correctly, price controls in the 70s were only on items subsidised by the government. To whom do I apply for the subsidy on my rental properties?
Member Since January 2020 - Comments: 1126 - Articles: 1
3:37 PM, 4th November 2026, About 7 days ago
Reply to the comment left by Steve Rose at 03/11/2026 – 19:48
You don’t have to look far to find politicians claiming that housing benefit is a subsidy to landlords.