

The PBSA “net yield” model — who in the chain is actually paid on net?
I want to set out a structure rather than a grievance, because I think landlords need to see it before they buy a pod.
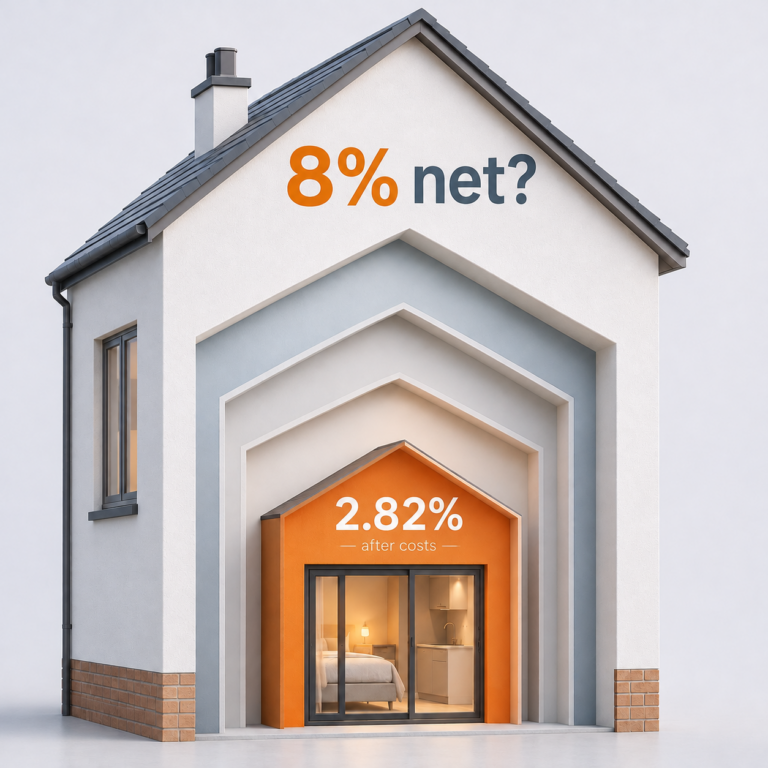
I reserved a studio for £70,700. The reservation document from the agent states: “8% NET GUARANTEED RENTAL INCOME FOR 2 YEARS.”
The particulars put a “Net Annual Income” of £5,381 on it. The £5,381 is £5,656 rent less £275 ground rent. That is the only deduction shown in that calculation. The service charge of £2,762 a year and the management fee of £626 a year are not included.
If those charges are payable in addition, and all the figures relate to the same year, the resulting net income is £1,993: a yield of approximately 2.82%. Even the stated £5,381 represents 7.61% of the purchase price, rather than 8%.
Here is the part that took me years to see. £5,656 ÷ 8% = £70,700 exactly. The quoted annual rent is exactly 8% of the purchase price. That does not establish how the price was originally set, but it makes the distinction between gross and net important.
At an illustrative 6% net yield, £5,656 of sustainable annual net income would support £94,267. But that calculation only works if £5,656 really is the income remaining after the relevant costs.
And the rent gets paid. The guarantee was honoured for its term. My concern is therefore not arrears, but capital value once the guarantee ends.
Using the calculated net income of £1,993, illustrative net yields of 7%–6% produce values of £28,471–£33,217 against £70,700 paid—a difference of approximately £37,483–£42,229. These are illustrations, not independently established market valuations. The appropriate yield and sustainable income would both need verifying.
A seller facing a substantial shortfall may prefer not to sell, potentially making resale values harder to establish.
Note also how the parties in the chain are paid. The operator collects the service charge, although that should not automatically be treated as its profit. There is also the £626 management fee.
Separately, the quoted rent of £153 a week would produce £7,956 over 52 fully paid weeks. Against that figure, £626 represents a management fee of approximately 7.87%, and the annualised gross yield is approximately 11.3% of the purchase price. This is a different income figure from the £5,656 used above and should not be confused with it.
If the agent earns a commission based on the sale price, its payment is not directly linked to the investor’s eventual net income. The investor receives what remains after costs. My concern is whether the incentives adequately protect that residual income, rather than simply making the headline yield attractive.
One further detail: the reservation document says two years. An investor update refers to a five-year assured period. It is worth checking which period applies, and when it starts, on any scheme.
To be fair to the operator, it does now publish a “Net payout yield” in its investor reports, so the concept exists. It was not the figure on which I understood the investment was being sold to me.
If you bought on an advertised net yield, I am coordinating complaints and would welcome hearing about similar experiences. The appropriate redress scheme, the relevant business’s membership and eligibility for a complaint need checking. The Property Redress Scheme is free for complainants and can award up to £25,000. propertyredress.co.uk
Complaint deadlines and any court limitation period also need checking separately. A court deadline should not simply be assumed to fall six years after reservation. propertyredress.co.uk
Not a solicitor. Just trying to reconcile the arithmetic.
Lord Cummins
Be the first to comment
Your experience could help the next reader
Have you dealt with something similar? Share what you learned, raise a question or offer a perspective your peers may find useful.
Previous Article
My rental flats were my income. Now I’m hanging on by my fingernailsNext Article
Tax changes prompt landlord sale plans
Not a member yet? Join In Seconds
Login with