

Beyond Help to Buy: why alternative routes onto the ladder now matter more than ever
Article by Peter Hawley, Director, SOWN (part of LRG)
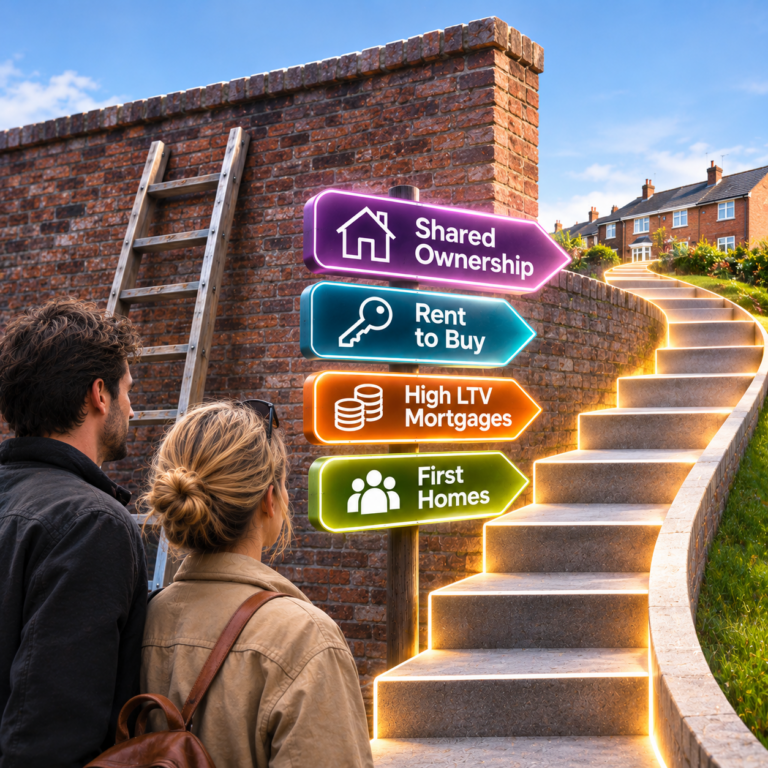
For many younger buyers, the property ladder no longer looks like a ladder: it looks like a wall.
The aspiration to own has not disappeared but what has changed is the distance between that aspiration and the practical ability to act on it.
Rents remain high, deposit saving is slower, mortgage affordability shows little sign of improving this year and the gap between incomes and house prices has widened in many parts of the country. For a generation that has studied, worked, saved and planned the reward of homeownership feels unrealistic.
This matters not only for individuals, but for the wider mortgage and property sector. If younger buyers conclude that homeownership is unrealistic, they disengage and this is exactly what needs to be addressed.
Rebuild confidence
For us, the added challenge is not simply to help those who are already mortgage-ready but to rebuild confidence among those who are not quite ready and need a more realistic pathway. That is where alternative routes onto the ladder become so important.
The end of Help to Buy left a substantial gap. Whatever one’s view of the scheme, it was successful in giving first-time buyers a route into new build ownership with a smaller deposit and it made that route highly visible. It had a recognisable brand, a simple message and the authority that comes with government backing, appealing to buyers, lenders and developers.
We now have a void in the space where Help to Buy previously existed. There are still options (high loan-to-value mortgages, First Homes, Rent to Buy and Shared Ownership) but from the buyer’s point of view, it’s a more fragmented and confusing picture.
Shared Ownership deserves a much larger place in this conversation. It is an established tenure that enables eligible buyers to purchase a share of a home and pay rent on the remaining share, with the opportunity to increase ownership over time. For those who cannot buy outright but want the security and discipline of ownership, it can provide a practical bridge between renting and full ownership.
Partly due to the affordability crisis, the profile of the shared ownership buyer is changing. Traditionally, the tenure was most closely associated with younger first-time buyers, particularly those in their mid-20s to mid-30s but we are seeing people who might once have used Help to Buy, would-be outright purchasers who have been priced out by higher mortgage and deposit costs and households who earn too much for some forms of housing support but too little to buy in the open market.
The average age of a Shared Ownership buyer is now mid to late thirties.
This “missing middle” is one of the most important affordability challenges facing the sector. In high-value areas, there are households with solid incomes who still cannot buy without assistance. Some are key workers, but an increasing number of professionals are now looking to Shared Ownership.
If the property sector is serious about supporting younger buyers, it must acknowledge that affordability is not uniform and a product that works in one region may be insufficient in another. The future is unlikely to lie in one flagship scheme, but in a more varied toolkit that reflects how differently affordability is experienced across the country.
The industry cannot solve this alone
That is why Shared Ownership thresholds and eligibility rules need continued scrutiny. The industry cannot solve this alone, but it can do more. Advisers, lenders, housing associations, developers and specialist sales teams should treat alternative routes into ownership as mainstream advice, not a niche afterthought.
That means explaining them earlier, more clearly and with less jargon; helping buyers understand deposits, rent, service charges, staircasing, resale processes and long-term affordability and being honest about limitations. Shared ownership is not the answer for everyone, but it should be considered by far more people than it currently is.
If Help to Buy demonstrated anything, it is that consumer awareness changes behaviour. Shared Ownership needs clearer national communication, better signposting and stronger policy recognition. At present, too much responsibility sits with individual providers and advisers. A more coherent national message would help build trust, tackle myths and give younger buyers the confidence to ask informed questions.
There is no single replacement for Help to Buy. The market has moved beyond the idea that one product can meet every affordability challenge. But that should not lead to drift. Younger buyers need a range of realistic options, explained properly and supported consistently.
We must stop treating homeownership as a binary choice between renting and buying: for many younger people, the first step onto the ladder may be smaller, more gradual and more structured than it was for previous generations.
The real test is whether the industry can meet buyers where they are, rather than where we wish they were. Shared Ownership, alongside other alternative models, offers one of the clearest ways to do that.
Peter Hawley has worked in the property industry for over 20 years (joining LRG in 2012) and is Director of SOWN shared ownership at LRG since 2019.
Be the first to comment
Your experience could help the next reader
Have you dealt with something similar? Share what you learned, raise a question or offer a perspective your peers may find useful.
Previous Article
Social housing landlord faces independent RSH inquiryNext Article
UK house price recovery delayed until 2028
Not a member yet? Join In Seconds
Login with