Company landlords are six times as likely to buy as those who own in their own name
1 month ago | 3 comments


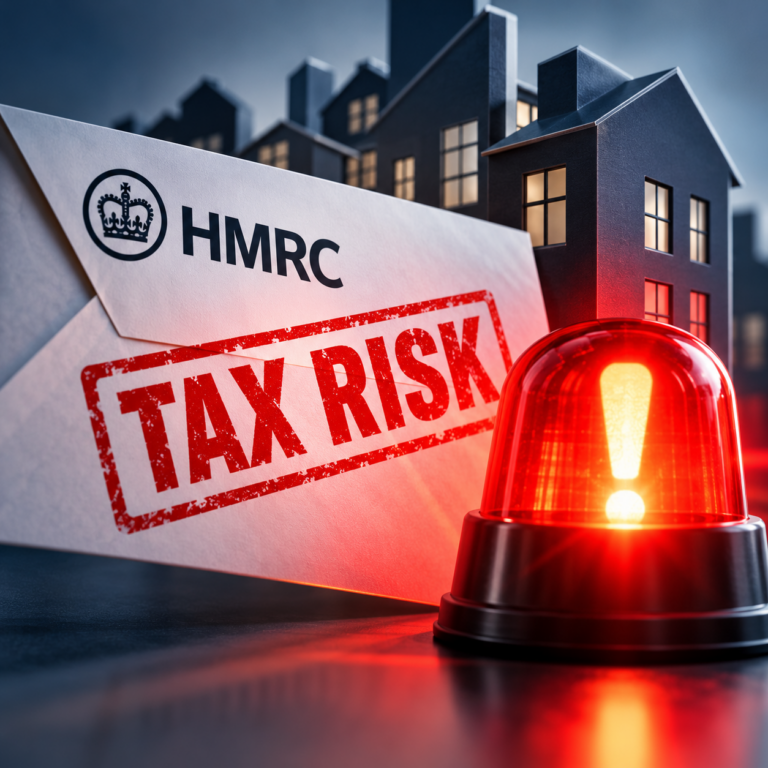
Company landlords will have reason to check their personal tax records as HMRC writes to company owners about potential self-assessment errors, but these letters are not compliance checks.
A personal bill paid from the company account could be as relevant to that review as a property transferred into the business.
The campaign, highlighted by the Institute of Chartered Accountants in England and Wales (ICAEW), concerns individuals identified as persons with significant control (PSCs).
Depending on their dealings with the company, they may have income or gains to report on their own tax returns.
The campaign is not aimed specifically at landlords, and the published material does not say whether all PSCs are being contacted.
For landlords, the company’s tax affairs and the owner’s personal tax position need separate consideration. Transactions between the two may affect what the owner needs to declare.
HMRC’s specimen letter identifies several potential issues, including personal expenses paid by the business without reimbursement and the private use of company assets without paying the market rate.
It also flags transfers of assets into or out of a company, certain loans and disposals of shares, property or other assets. These are matters to review, rather than evidence that tax is necessarily outstanding.
Under Companies House guidance, a PSC will usually hold more than 25% of a company’s shares or voting rights, have the right to appoint or remove a majority of directors, or otherwise exercise significant influence or control. A company can have more than one PSC.
For a landlord preparing to discuss the letter with their accountant, a useful starting point would be:
Together, these should help the accountant establish what happened and how it was reported.
HMRC wants recipients to ensure their 2025/26 self-assessment return is correct and review earlier years.
ICAEW explains that errors for 2024/25 can be addressed by amending the return, while the digital disclosure service is the route identified for 2023/24 and earlier years. The campaign requests action before 31 January 2027.
Recipients satisfied that their return is correct do not need to take further action or contact HMRC.
The letter also warns that, if HMRC subsequently finds relevant errors or undisclosed tax, it will treat any disclosure as prompted, which may affect penalties.
The dedicated email address provided in the letter closes on 27 November 2026, ahead of the January deadline for action.
Be the first to comment
Have you dealt with something similar? Share what you learned, raise a question or offer a perspective your peers may find useful.
1 month ago | 3 comments
3 months ago | 3 comments
2 months ago | 4 comments
Not a member yet? Join In Seconds
Login with